Branch vs PLC in Ethiopia: What Foreign Investors Must Know
Sun, 25 Jan 2026
Follow the stories of academics and their research expeditions
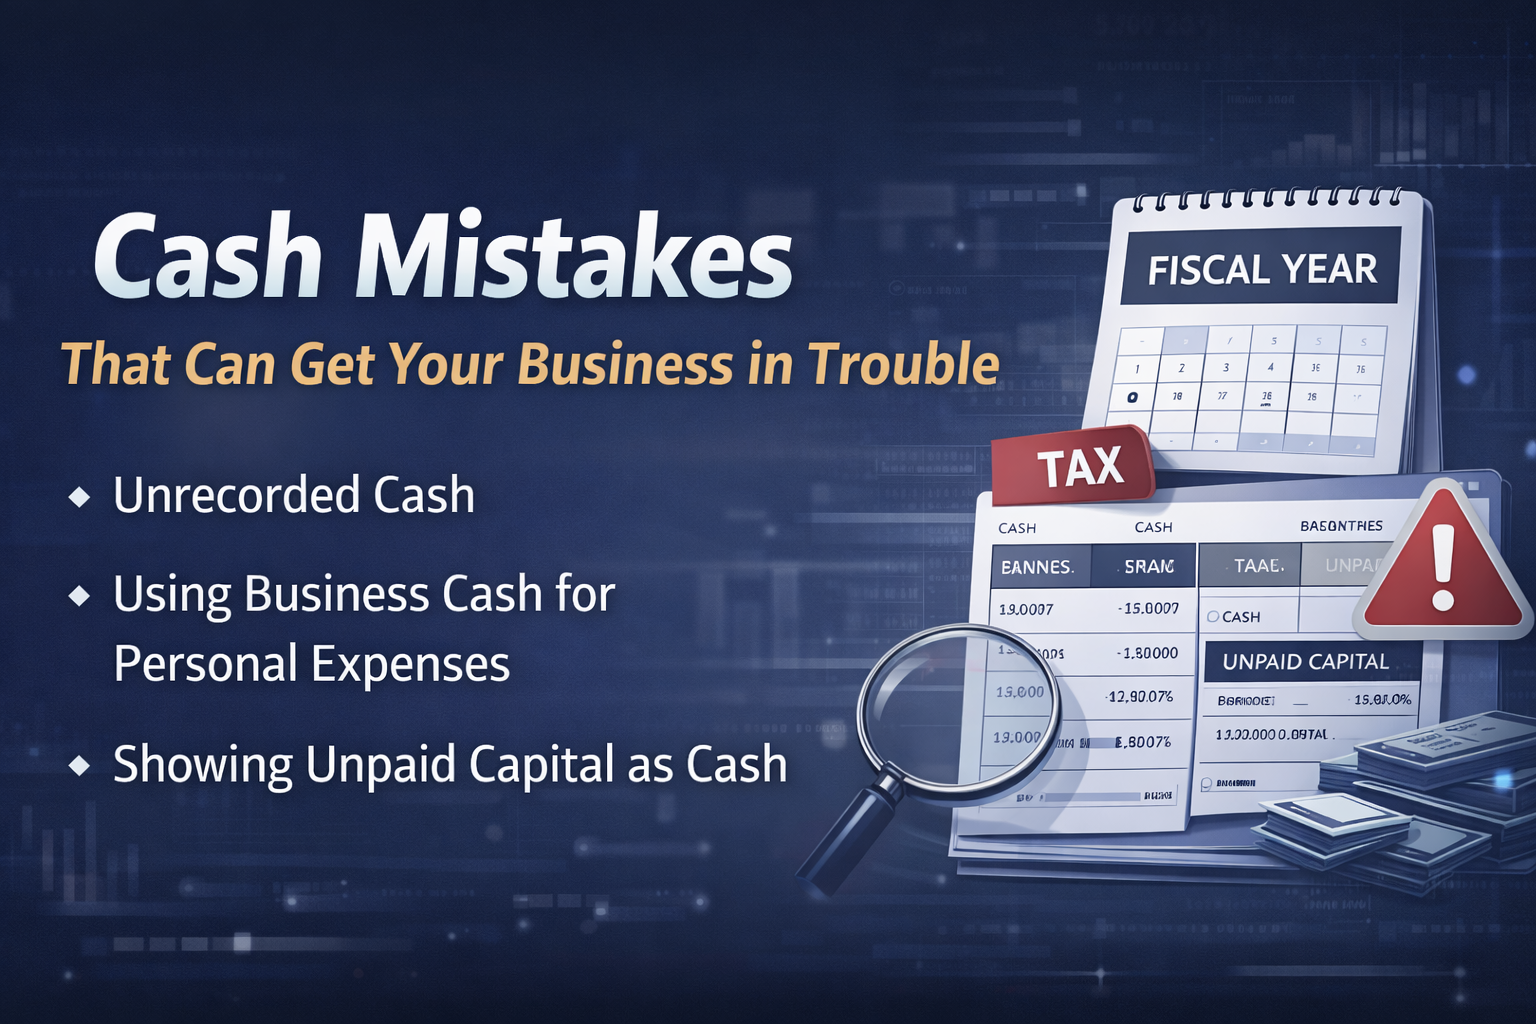
For many businesses in Ethiopia, cash feels straightforward. Money comes in. Money goes out. If there’s cash in the books, it must be there somewhere.
But this is where many businesses get into trouble.
Tax auditors, especially those following guidance from the Addis Ababa Revenues Bureau, pay very close attention to cash. And one issue keeps showing up again and again: cash that exists on paper but not in real life.
This article explains the most common cash mistakes and how business owners can avoid them.
At the end of the financial year, the cash shown on your balance sheet must match what you actually have:
In your bank accounts
In your safe or petty cash
If your books show 2 million birr but you can only prove 600,000 birr, the remaining amount becomes a serious problem.
From the tax authority’s point of view, missing cash usually means one of three things:
The owner took money but didn’t record it
Income was earned but not reported
The accounts were overstated to look stronger
Once this happens, the business must explain the difference. If it can’t, tax follows.
Many business owners use company money to cover personal costs like rent, school fees, or family expenses. This is very common and not automatically wrong.
The problem starts when:
The withdrawals are not recorded, or
The owner takes more than the business actually earned
If a business makes 500,000 birr in profit but the owner takes 900,000 birr, the extra 400,000 birr has no clear explanation. Tax authorities often treat this excess as unreported income.
The simple rule is this:
Owners can only take money equal to profits made or capital invested.
Anything beyond that creates risk.
Another common mistake happens when a business records capital that was never actually paid into the business.
On paper, everything looks fine. In reality, there is no cash.
Some businesses show this as “receivable from the owner,” but tax authorities do not treat this as real cash. If the money is not in the bank or physically available, it should not appear as cash in the accounts.
If capital was registered but never paid:
Pay it in properly, or
Adjust the records to match reality
Showing “promised money” as cash makes a business look stronger than it is, and that can cause problems during audits or license renewals.
Some owners believe they can sort things out at year-end. That approach does not work.
If business money is used for personal reasons:
It must be recorded right away
It must be supported by evidence such as bank transfers, checks, or deposit slips
Unrecorded personal spending creates fake cash balances. During an audit, this almost always leads to adjustments and extra tax.
Cash problems don’t only come from withdrawals. They also come from accounting mistakes.
Two big ones are:
Recording imports at the wrong value
Imports must be recorded using the customs value, not a lower supplier invoice. Using the wrong figure creates unexplained differences that inflate cash or equity.
Ignoring foreign exchange gains or losses
When exchange rates change between ordering and paying for imports, the gain or loss must be recorded as income or expense. Leaving it in cash-related accounts quietly creates false balances.
These errors often go unnoticed until an audit, when they suddenly become expensive.
Cash issues become even more serious when a business shuts down.
If, at closure, the owner has taken more money than:
The capital they invested, plus
The profits the business earned
The excess is treated as taxable income.
Many business owners are surprised by this at the final stage, when it is hardest to fix.
Good cash management does not require complex systems. It requires consistency.
Strong businesses usually:
Reconcile cash and bank balances regularly
Record owner withdrawals immediately
Avoid showing unpaid capital as cash
Close owner withdrawal accounts at year-end
Use correct values for imports
Record foreign exchange differences properly
These habits reduce audit risk and give a clearer picture of how the business is really performing.
Most businesses that face cash-related tax problems did not intend to break the rules. They simply let small issues build up over time.
Cash may seem simple, but it is one of the most closely checked areas in tax audits. Keeping your cash records honest, supported, and up to date protects your business, your reputation, and your peace of mind.
If the cash is real, the numbers will speak for themselves.
Sun, 25 Jan 2026
Fri, 16 Jan 2026
Thu, 15 Jan 2026
Apex Study any topic, anytime. explore thousands of courses for the lowest price ever!
Leave a comment